fintech IRELAND
email / social
  • Home
  • Fintech Authorisations
  • Fintech Education & Training
  • Fintech Ireland Map
    • Fintech Survey
  • Events
    • Summit
    • Events-Archive
  • Fintech Hub
  • News-Insights
    • Consultations
    • News Page Back Up
  • Careers
  • RegTech
  • CRYPTO
  • Fundraising
  • Brexit & Ireland
  • About
    • Fintech Family Network
  • Get Involved

Cohort #1 of Central Bank of Ireland’s Innovation Sandbox Programme: ‘Combatting Financial Crime’

9/1/2025

0 Comments

 
Picture
See CompliReg at ​https://complireg.com/blogs--insights/cohort-1-of-central-bank-of-irelands-innovation-sandbox-programme-combatting-financial-crime for detailed blog

Seven participants of the Central Bank of Ireland’s Innovation Sandbox Programme on ‘Combatting Financial Crime’ are:

1) AMLYZE is building an AML/CFT information-sharing framework that will use structured taxonomies and synthetic data to simplify detecting and preventing fraudulent activities.

​2) Expleo Group has developed an anti-SMS fraud solution which installs on mobile phones to combat SMS fraud.

3) Forward Emphasis and Pasabi’s joint innovation will develop and test a Motor Insurance Application Fraud Analytics solution, leveraging AI-driven behavioural analytics, machine learning, and pattern recognition to detect fraud in the pre-sales process.

4) Roseman Labs enables secure, GDPR-compliant collaboration and analysis on sensitive data for regulated industries.

5) Sedicii (hello Rob Leslie) and PTSB Sedicii has partnered with PTSB to create a secure and private collaboration using zero knowledge proofs to verify names and addresses, in real-time, as part of their customer KYC process, using ESB Networks as the authority for address data in Ireland in full compliance with GDPR and which involves no sharing of personal data.

6) TrustElevate.com offers a privacy-preserving solution for verifying parental responsibility and child age.

7) Vidos.Id is developing digital identity verification solutions to help financial institutions verify digital identity documents and wallet-based credentials.

​See CompliReg at ​https://complireg.com/blogs--insights/cohort-1-of-central-bank-of-irelands-innovation-sandbox-programme-combatting-financial-crime for detailed blog

​See CompliReg at ​https://complireg.com/blogs--insights/cohort-1-of-central-bank-of-irelands-innovation-sandbox-programme-combatting-financial-crime for detailed blog
0 Comments

Sors Digital Assets and Crypto.com secure VASP licences in Ireland.  Version 11 of Regulated Fintech Map and Version 8 of the VASP Map released.  Ireland is now home to at least 75 regulated fintechs

19/7/2024

0 Comments

 
Picture
Click the above image for a larger image
  • Sign up to our Newsletter here.​
  • Need assistance with an emoney or payments authorisation or an account information service provider or virtual asset services provider registration application, check out Fintech Ireland and CompliReg's handy authorisation guides at https://fintechireland.com/fintech-authorisations.html. 
  • Attend, exhibit and/or sponsor the upcoming Fintech Ireland Summit.  Details here. 

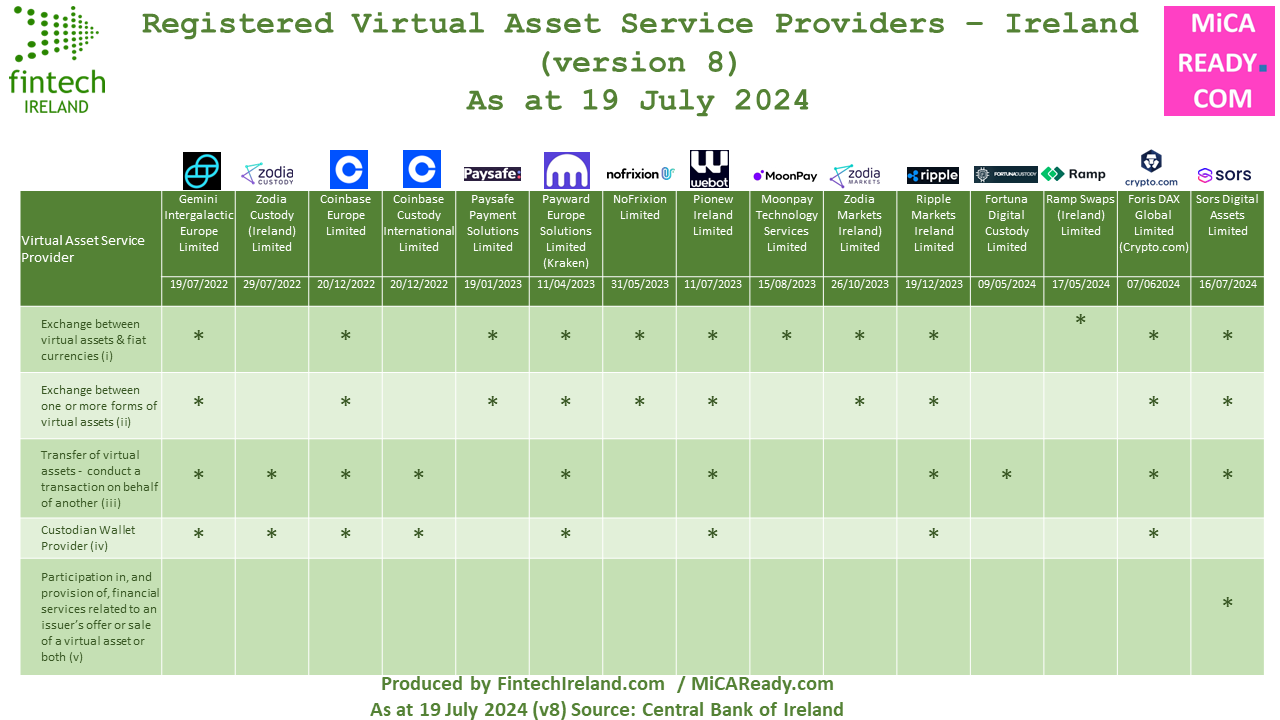
​ Foris DAX Global Limited (aka Crypto.com) and Sors Digital Assets Limited

Ireland is now home to at least 75 regulated fintechs with the registrations of both Foris DAX Global Limited (aka Crypto.com) and Sors Digital Assets Limited.  The two companies were registered by the Central Bank of Ireland under the Criminal Justice (Money Laundering and Terrorist Financing) Act 2010 as virtual asset service providers.  To remind, VASPs are not authorised but registered to provide their services.

Linkedin Post here: https://www.linkedin.com/posts/peteroakes_cryptoasset-virtualasset-micar-activity-7219828976863641601-fNxw

Fintech Ireland is delighted to welcome both firms to the ever-growing Regulated Fintech Map (Version 11) and the VASP Map (version 8).  Thanks to CompliReg and MiCA Ready which support firms in the  in the #cryptoasset / #virtualasset industry.

By the way, did you know that today (19 July 2024) is the second anniversary of the very first registration of a VASP?  That honour belongs to Gemini Intergalactic Europe Limited which was registered on 19 July two years ago.  Happy anniversary!

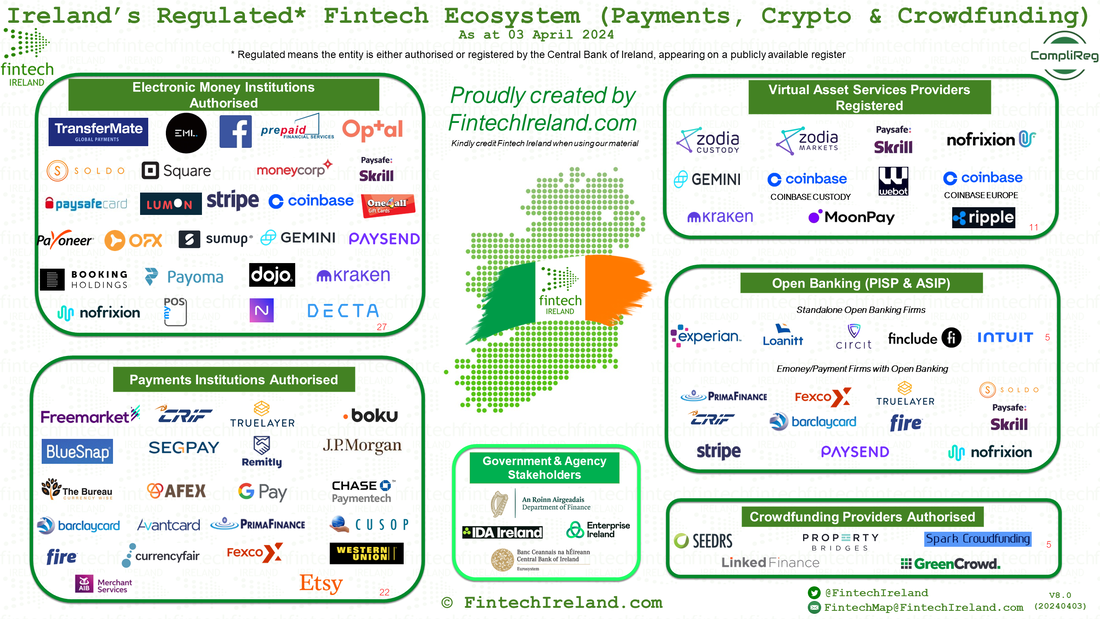
This registration of Crypto.com on 7 June 2024 and Sors Digital Assets on 16 July 2024 increases the pool of regulated fintech in Ireland to at least 75, comprised of:

* 27 authorised electronic money institutions
* 22 payments institutions,
* 6 standalone open banking firms,
* 15 VASP, and
* 5 crowdfunding services providers.

Those who read the recent Authorisation and Gatekeeping Report issued by the Central bank of Ireland might recall:

  • that as at 31 December 2023 there were 14 applicants for a VASP registration in the pipeline as at that date.  Obviously deduct 2, and that means if there have been no withdrawals and no new applications, we might see a further 12 firms become registered before year’s end.  If that is the case the Central Bank will have its work cut out for itself dealing with potentially 27 MiCAR applications. Of course, it would be wise to assume that further companies have applied for registration since the start of this year.
  • the average number of days taken to register a VASP is 530 calendar days and is largely driven by time taken by the applicants to respond to queries raised during the assessment. A significant number of firms have withdrawn from the registration process. 
Picture
Click the above image for a larger image
According to Companies Registration Office Records, Sors Digital Assets is a shareholder (32.67%) in Fortuna Digital Custody Ltd which was registered as a VASP by the Central Bank of Ireland earlier this year on 9 May 2024.  Sors Digital Assets is owned by Brian Elders (55%) and Stephen Browne (45%).  Brian Elders is a director of both Sors Digital Assets and Fortuna Custody Ltd.  Sors Digital Assets had net assets of €769K as at 31 December 2023.  Stephen Browne is another director of Sors Digital Assets.

​Foris DAX Global Limited is wholly owned by  Foris Dax Holdings Ltd.  Its directors are Mariana Dinkova Gospodinova, Rafael De Marco E Melo and Antonio Alvarez Lorenzo.  Within the Crypto.com group, Mariana serves as EVP Operations & GM Europe; Rafael is co-founder and CFO; and Antonio is Group Chief Compliance Officer.  Crypto.com's VASP registered operations made a small overall profit (comprehensive income) of €71.4K in the year to 31 December 2022 well down on the €3.120M profit for the previous year.  The company's net assets as at 31 December 2022 were €3.2M.   

We wish both Crypto.com and Sors Digital Assets the very best success for their future endeavours.
​​

Don't forget to check out the upcoming Fintech Ireland Summit taking place on Thursday 28th November 2024 in Dublin. 

Picture
0 Comments

Authorisations and Gatekeeping Report Edition 1 - Issued by the Central Bank of Ireland

26/6/2024

0 Comments

 
Picture
Picture
We will be covering the topics of Central Bank of Ireland Authorisations and its role as Gatekeeper to the regulated Irish financial services community at the Fintech Ireland Summit taking place on Thursday 28 November 2024.  Read more here.
Central Bank of Ireland has today, Wednesday 26 June 2024, issued the first edition of the Authorisations and Gatekeeping Report. 

We posted about this on Linkedin here.  You can watch the movie of extracts from the Report here.

In this blog you can download a copy of the Authorisations and Gatekeeping Report (in the next link below and at end of blog).  We have copied and pasted the forward by Sharon Donnery, Deputy Governor, Central Bank of Ireland immediately below.
Picture
Sharon Donnery, Deputy Governor, Financial Regulation, Central Bank of Ireland
Foreword

Sharon Donnery, Deputy Governor, Financial Regulation 


I am very pleased to introduce the Central Bank of Ireland’s (“The Central Bank”) inaugural “Authorisations and Gatekeeping Report". The Central Bank regulates and supervises over 12,000 firms providing products and services in Ireland, the European Union (“EU”) and around the world. Our mission is to serve the public interest by maintaining monetary and financial stability while ensuring that the financial system operates in the best interests of consumers and the wider economy. 

A strong regulatory and supervisory framework, ensuring we have a stable, resilient and trustworthy financial sector, enables us to deliver on our mission for the public. Our gatekeeping role is an integral part of that framework – helping to ensure firms and individuals are of a sufficiently high standard to meet regulatory requirements and to be trusted with the public’s money. Since 2018, the Central Bank has either authorised or approved close to 12,000 applications across a range of financial service providers, prospectuses and regulated financial products and has approved over 18,000 applications for senior positions in the financial sector in Ireland as part of our Fitness and Probity (“F&P”) regime. In 2023 alone, we received almost 3,300 applications for authorisation or approval and over 3,300 applications for senior positions.


In order to ensure the system and the public are protected and that trust is maintained, gatekeeping, and the phrase “regulated by the Central Bank of Ireland”, has to mean something in terms of standards and reassurance to the people of Ireland. As such, the process needs to be robust, and the standard needs to be appropriately high. 

However, given the volume of applicants and the benefits of new entrants for consumers and the wider economy, to ensure the gate is not an undue barrier to entry it is also important that the process is efficient and that it is transparent.

As such in recent years as part of our ongoing commitment to efficiency and in the face of feedback that we could improve our clarity and responsiveness to incoming applications, we have increased engagement and significantly improved our processes. We have done this while maintaining the high standard the public expects of regulated providers of financial services and of us.

As I have said before this is not about prioritising speed over rigour, as the authorisation process is just the beginning of the regulatory and supervisory relationship, and our experience is that going through the gate too swiftly often presents issues on the other side.

Recognising that
better prepared firms find the authorisation process the most straightforward, in addition to increasing the efficiency and transparency of our own processes we have improved our communications and have set clearer expectations for firms. This aims to deliver better and more complete applications to the benefit of both the applicants and the Central Bank, increasing the efficiency of the gate, while maintaining its robustness. Through this new report, we are providing further transparency to all stakeholders. The report sets out how we discharge and continue to refine our authorisation mandate by:
  • Providing information on our authorisation framework and risk appetite;
  • Explaining our priorities and expectations of applicant firms;
  • Providing insight into the operation of the F&P regime; and
  • Outlining the key challenges that we see for firms seeking authorisation. 

We hope it is useful for all stakeholders, and complements our other engagements and publications. Looking ahead, enhancing how we regulate and supervise across all sectors is a strategic priority of the Central Bank. This includes continuing to enhance our authorisation processes, in terms of clarity, predictability and transparency for those seeking to be authorised.

​We will continue to improve our own process as well as our engagement and communication with the sector. We also want to learn from experience and welcome feedback from stakeholders on our processes. 


END

Download the inaugural “Authorisations and Gatekeeping Report"

​We will be covering the topics of Central Bank of Ireland Authorisations and its role as Gatekeeper to the regulated Irish financial services community at the Fintech Ireland Summit taking place on Thursday 28 November 2024.  Read more here.
0 Comments

Intuit Ireland Software obtains an open banking registration in Ireland.  Version 8 and 19 of Regulated Fintech Maps released showcasing 69 regulated fintechs.

3/4/2024

0 Comments

 
Picture
Picture
Click for a larger image
​Sign up to our Newsletter here.​
  • Need assistance with an emoney or payments authorisation or an account information service provider or virtual asset services provider registration application, check out Fintech Ireland and CompliReg's handy authorisation guides at https://fintechireland.com/fintech-authorisations.html.  
LinkedIN Post here - https://www.linkedin.com/posts/peteroakes_fintech-electronicmoney-paymentservices-activity-7181459570395877376-2pN3
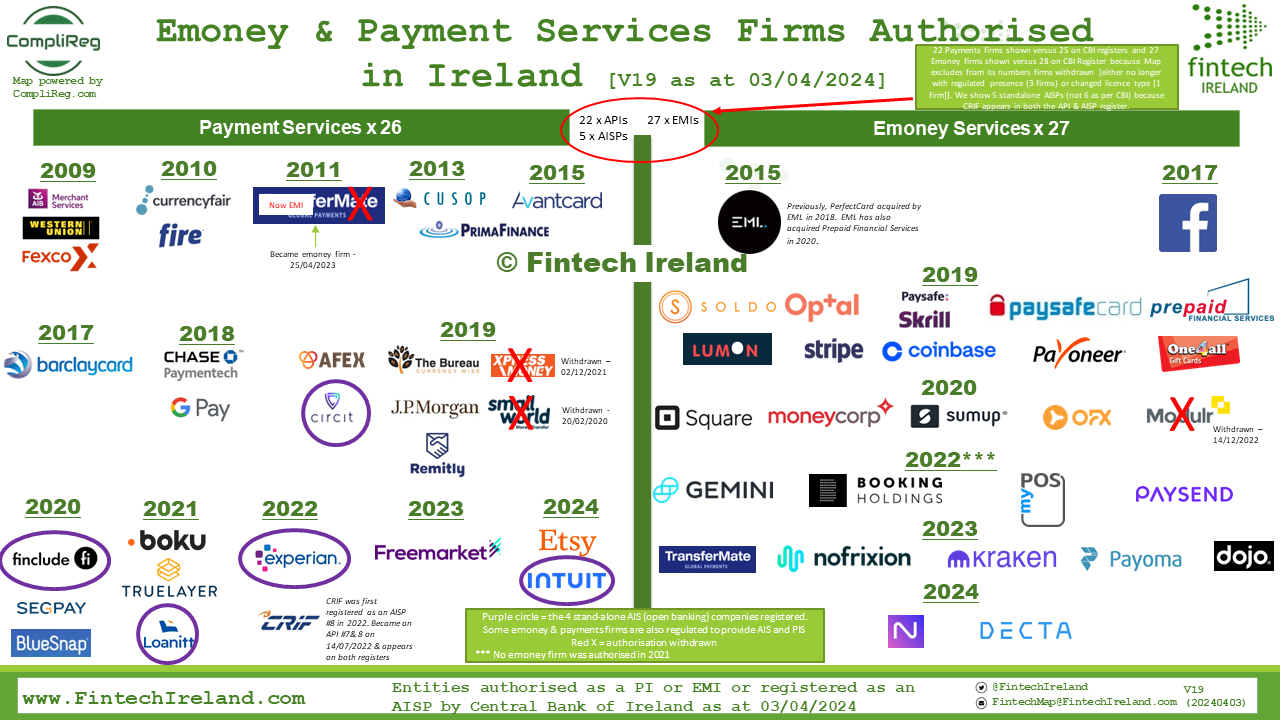
​Welcome Intuit Ireland Software Limited to the regulated fintech ecosytem in Ireland!  Its authorisation brings the pool of regulated fintech in Ireland to 69, comprised of:
​
  • 27 authorised electronic money institutions
  • 21 payments institutions,
  • 5 standalone open banking firms
  • 11 virtual asset services providers and
  • 5 crowdfunding services providers. 
​Intuit Ireland Software Limited registration is the 1st standalone open banking firm to be registered in Ireland since July 2022. 

The company was incorporated in Ireland just under one year ago on 6 April 2023. and was registered by the Central Bank of Ireland on 2 April 2024.

Ireland now has 16 entities which are authorised or registered to provide open banking services.  These include 5 standalone entities and a mix of 11 emoney and payment firms which can provide such services. 

As we said back on 20 February 2024, we are pretty sure that these numbers will continue to grow in 2024.

Intuit Ireland Software Limited  has been registered by the Central Bank of Ireland to provide payment services #8 (Account information services) ​
Picture
​Intuit Ireland Software Limited is owned 1005 by Intuit Inc.
LinkedIN Post here - https://www.linkedin.com/posts/peteroakes_fintech-electronicmoney-paymentservices-activity-7181459570395877376-2pN3
​
  • Sign up to our Newsletter here.
  • Need assistance with an emoney or payments authorisation or an account information service provider or virtual asset services provider registration application, check out Fintech Ireland and CompliReg's handy authorisation guides at https://fintechireland.com/fintech-authorisations.html.  
0 Comments

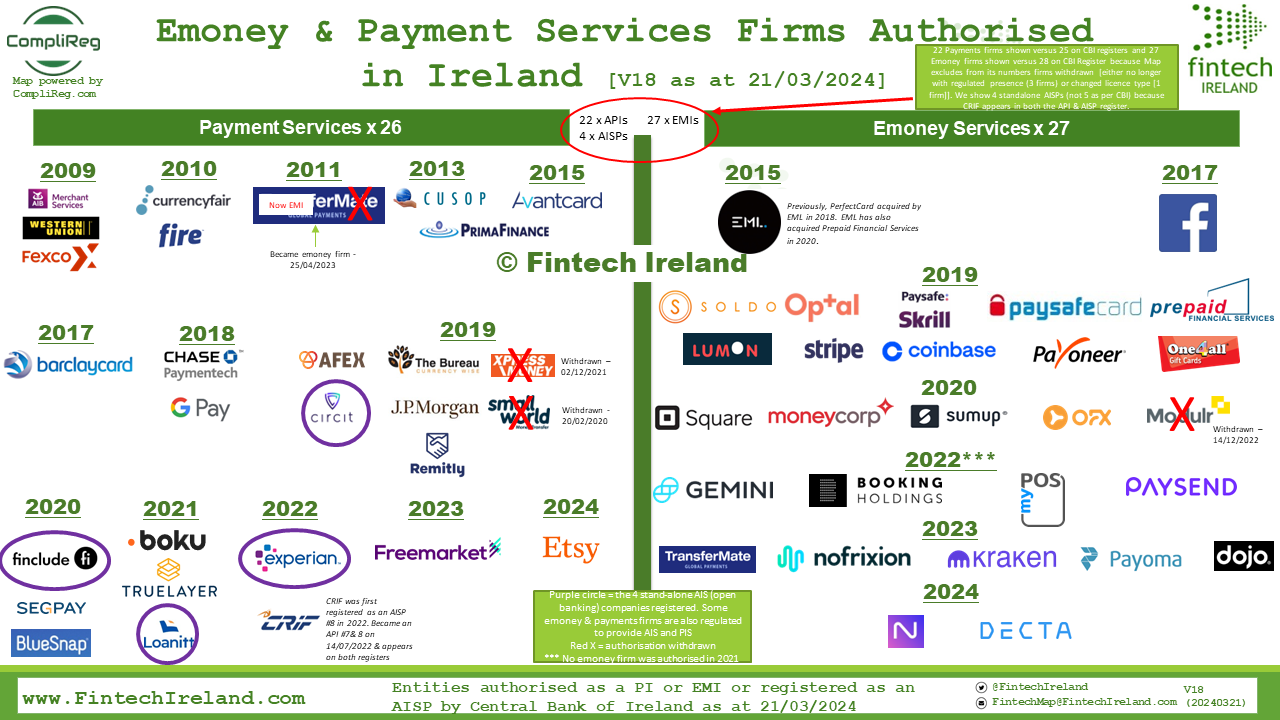
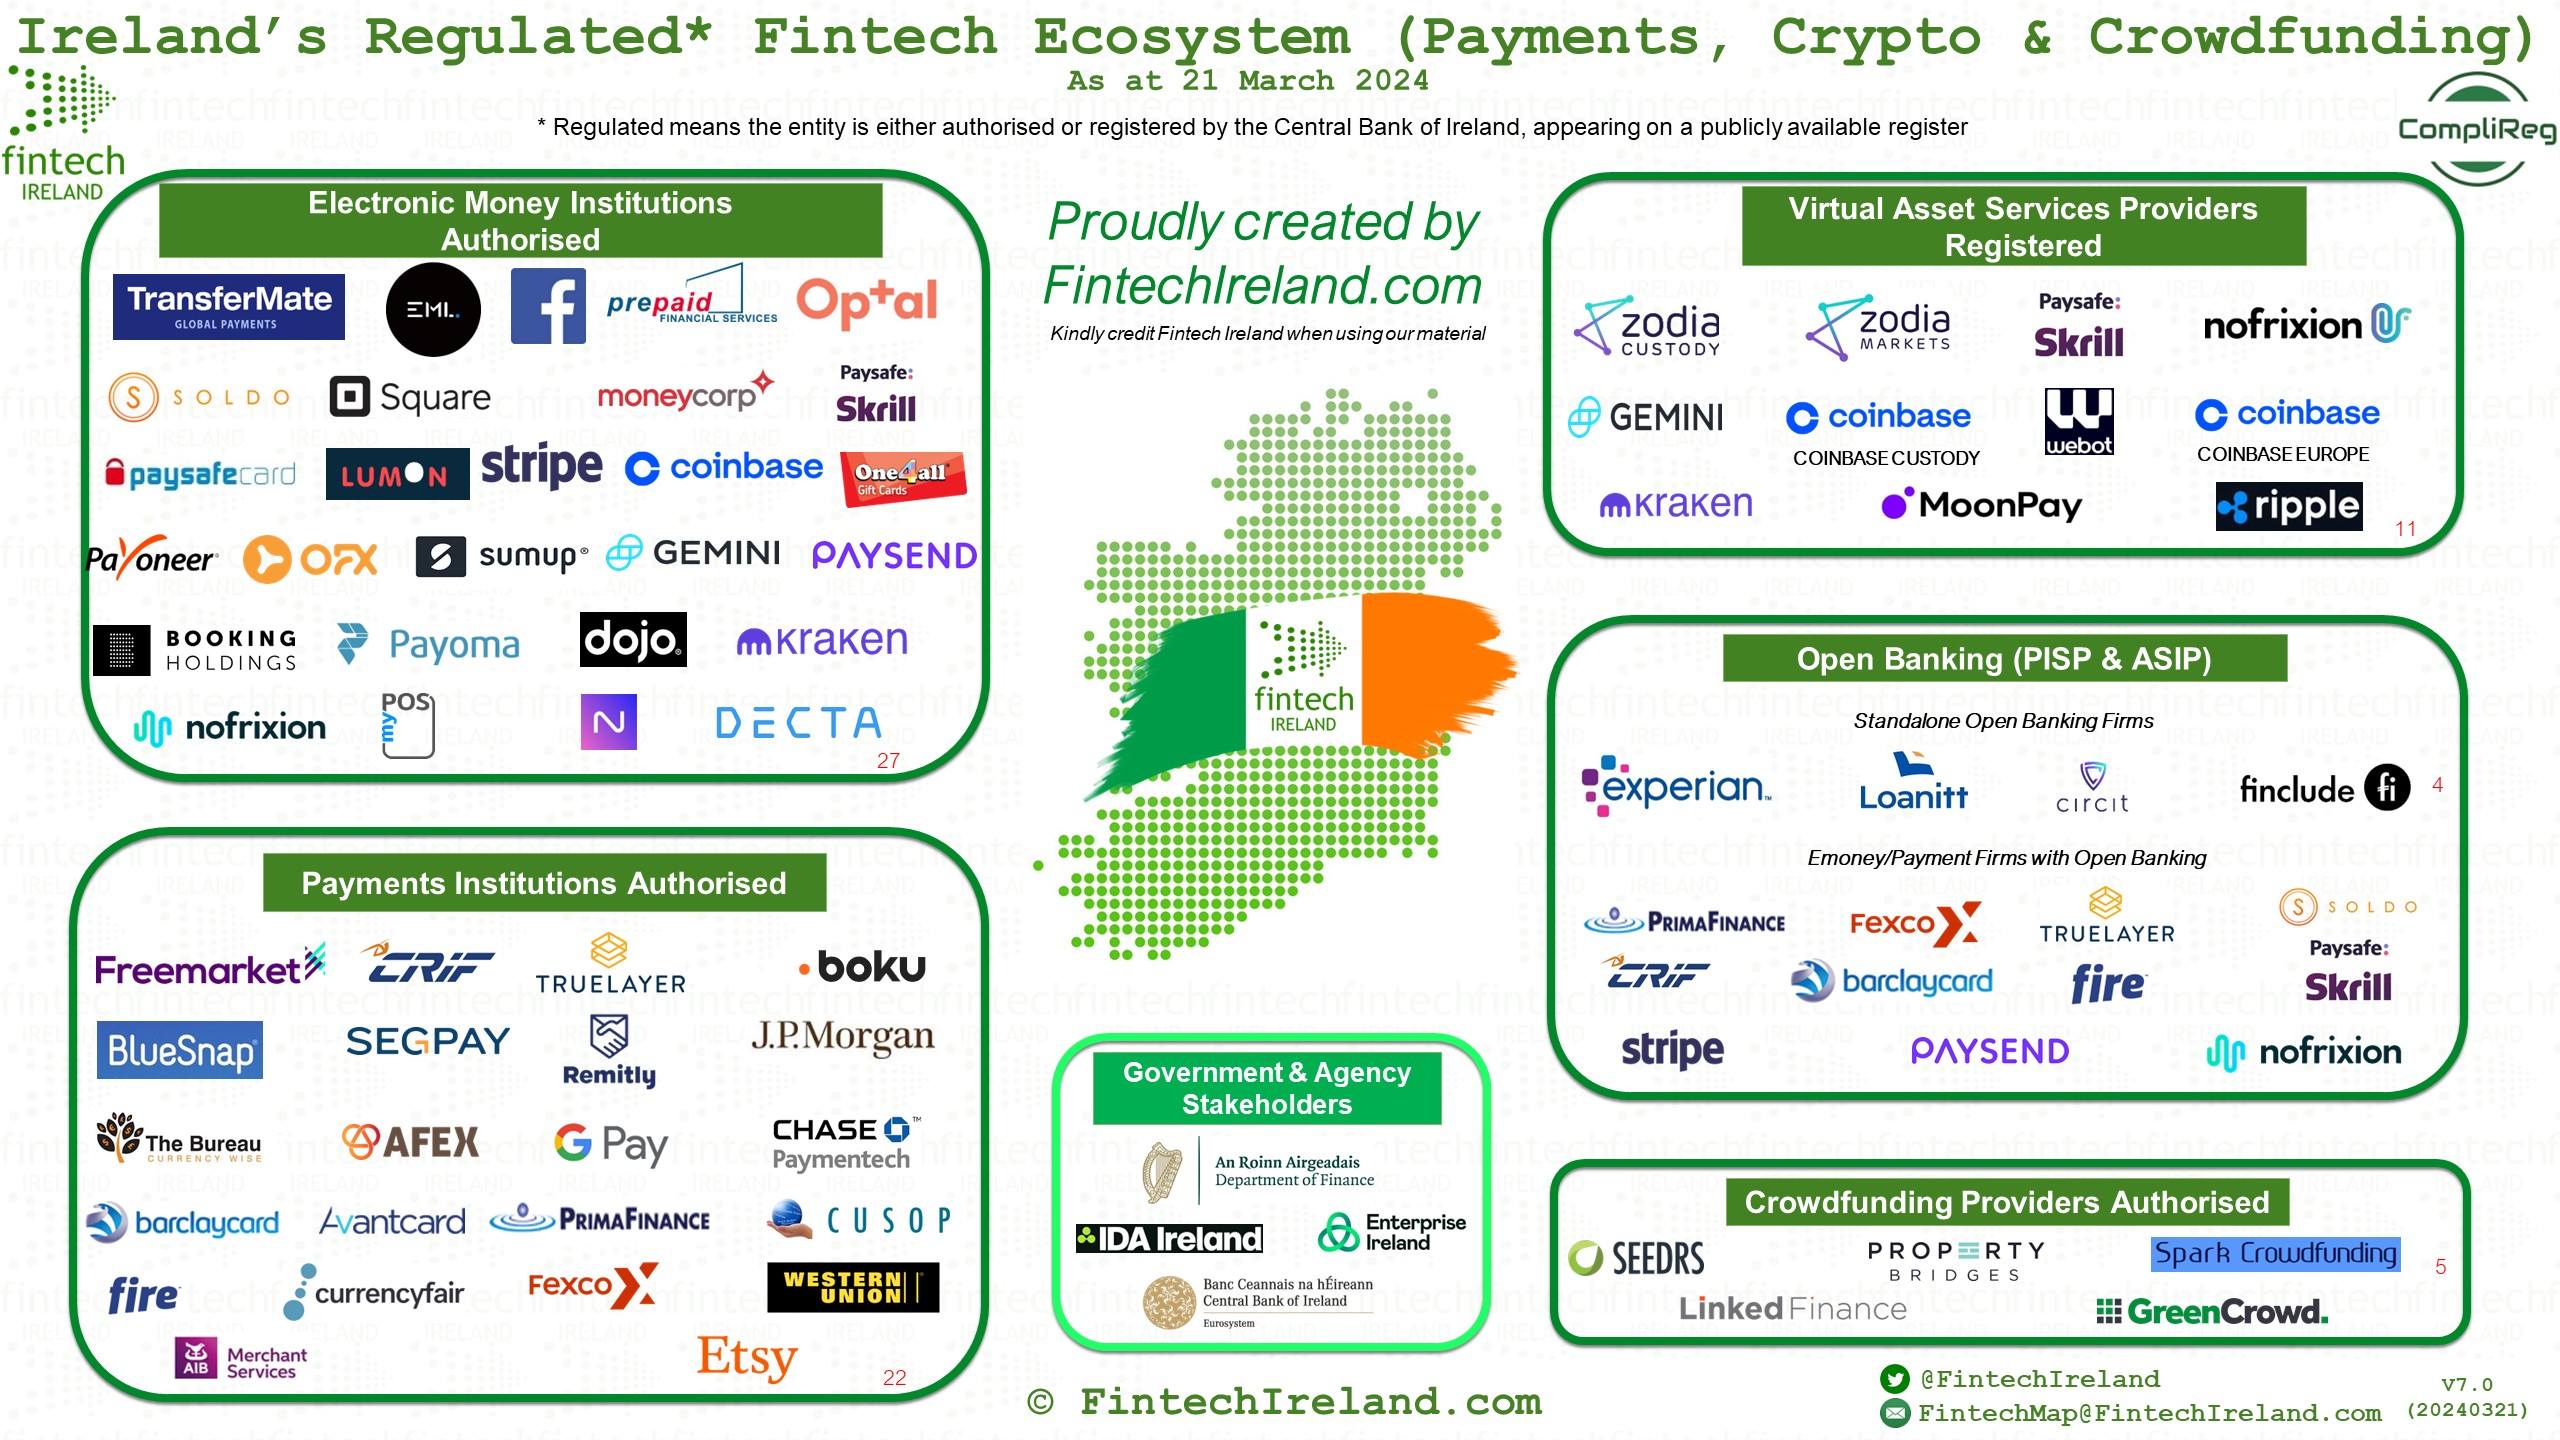
Decta obtains an emoney authorisation in Ireland.  Version 7 and 18 of Regulated Fintech Maps released showcasing 68 regulated fintechs

21/3/2024

0 Comments

 
Picture
Click for larger image
Picture
Click for larger image
  • Sign up to our Newsletter here.
  • Need assistance with an emoney or payments authorisation or an account information service provider or virtual asset services provider registration application, check out Fintech Ireland and CompliReg's handy authorisation guides at https://fintechireland.com/fintech-authorisations.html.  
LinkedIN Post here - https://www.linkedin.com/posts/peteroakes_fintech-electronicmoney-paymentservices-activity-7176891077675626497-X-ZI

Welcome Decta Limited to the regulated fintech ecosytem in Ireland!  Its authorisation brings the pool of regulated fintech in Ireland to 68, comprised of:
  • 27 authorised electronic money institutions
  • 21 payments institutions,
  • 4 standalone open banking firms
  • 11 virtual asset services providers and
  • 5 crowdfunding services providers. 
Decta Limited's authorisation is the 2nd emoney institution to be authorised so far this year. The most recent payments company authorised was Etsy Ireland Limited and previous to that it was emoney firm Navro Payments Europe Limited.

As we said back on 20 February 2024, we are pretty sure that these numbers will continue to grow in 2024.

In what must have felt as extended St Patrick Day's long weekend for the Irish Decta Team, the company was authorised by the Central Bank of Ireland on Tuesday 19 March 2024 as an emoney institution. 
Decta Ireland has been authorised to provide emoney services and payment services #3c (Execution of credit transfers, including standing orders) and #5 (Issuing of payment instruments and/or acquiring of payment transactions).
Picture
Decta Limited has been authorised to provide emoney services and payment services #3 (Execution of credit transfers, including standing orders) and #5 (Issuing of payment instruments and/or acquiring of payment transactions). 

Some observations:
  • ​Why did Decta seek an authorisation in Ireland when another Decta Limited became authorised in Cyprus for emoney services on 10 August 2023?
  • The Irish company was incorporated back on 1 October 2021.  That seems a long time from its incorporation date to today for an entity to become authorised - nearly 30 months. While a firm may not start an application immediately after it is incorporated, most firms - where they are the subsidiaries of foreign firms - start the journey no later than three to six months following incorporation.  If one was conservative and went with the six month timeline, it may have taken Decta Limited 24 months to become authorised.    
  • It appointed its first set of Irish resident NEDs on 1 June 2022, with one of them leaving just after Christmas Day 2023 following the appointment of another NED just before that Christmas period.
  • In addition to the NEDs, the company's local CEO sits on its board together with two group executives including its Cypriot authorised company's CEO and its Deputy CEO. 
  • The Irish comapny's shareholders are RRE Tradecenters Holding Limited based in Cyprus and SIA "Suharenko Family Investments" based in Latvia, holding 67% and 33% of the Irish company respectively.   
  • SIA "Suharenko Family Investments" is a shareholder in the Latvia Bank, AS “Rietumu Banka”.  
  • Irish billionaire Dermot Desmond owns a one-third stake in Rietumu Banka.  Its group profits fell 37pc to €11.4m in the first nine months of 2023.
  • Decta's operations in the UK, Decta Limited (UK), are authorised by the Financial Conduct Authority for emoney and payment services. 
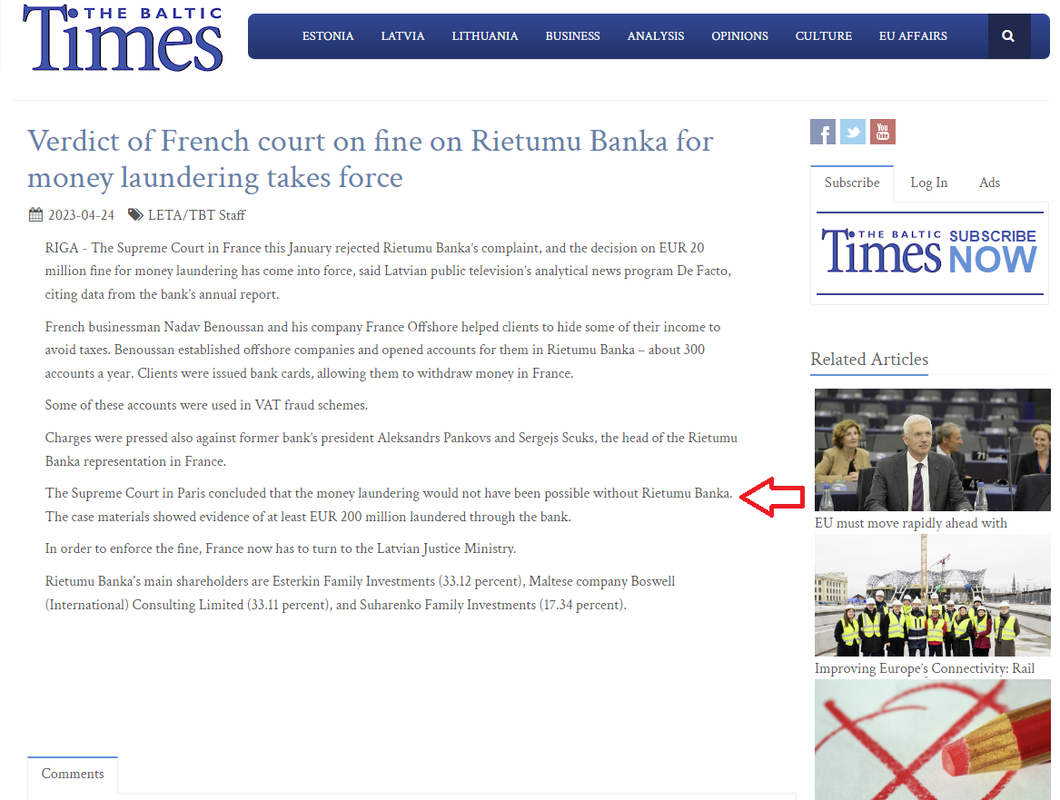
  • Decta was cited by Transparency International UK in a report focused upon financial crime risk.  The very informative report titled 'Together in Electric Schemes, Analysing Money Laundering Risk in E-Payments' was issued in December 2021.  The Bank was hit by two regulatory sanctions.  The largest sanction was a fine of €80mn later reduced by a French appeals court to €20mn.  According to The Baltics Times on 24 April 2023 "The Supreme Court in Paris concluded that the money laundering would not have been possible without Rietumu Banka. The case materials showed evidence of at least EUR 200 million laundered through the bank."  
  • According to CRO records for Decta Limited as at year end December 2022 the company incurred a loss of €114.1K, had Net Current Assets of €46.9K and Net Liabilities of €110.6K.
The Decta brand was called out by Transparency International UK in a report focused upon financial crime risk.
Picture
​The Decta brand was called out by Transparency International UK in a report focused upon financial crime risk.  The very informative report titled 'Together in Electric Schemes, Analysing Money Laundering Risk in E-Payments' and issued in December 2021 carried a case study in which it noted that:

"[s]ome Latvian banks now own UK EMIs. Decta Limited, a UK EMI, lists its PSC as Rietumu Holding, the firm behind Rietumu Bank in Latvia.  In 2017, Rietumu was fined €80 million by French authorities after it was found to be involved in major tax and money laundering schemes. In response to an investigation by independent global media organisation, openDemocracy, Decta Limited stated it “acts in strict accordance with the requirements of FCA”, adding “we regularly pass anti-money-laundering (AML), Anti-Fraud, Know Your Customer and Combating the Financing of Terrorism audits held by Visa, Mastercard and big-four auditors, proving Decta to be complying with all latest AML standards.” 

In June 2021, Rietumu was fined again for money laundering failings in Latvia, this time in relation to its association with payment service providers, including those based outside of the country. A page on the website of Latvia’s central bank (Latvijas Banka), shows Rietumu has correspondent banking relationships with at least six UK EMIs.

It is becoming increasingly clear that British EMIs using Baltic banks for clearing services raises money laundering risk for both the UK and Baltic states. UK EMIs with unsuitable owners or weak AML controls are unlikely to carry out sufficient checks on their clients, while Baltic banks may believe firms regulated by the FCA have higher AML standards than they do in reality. This situation would lead to international payments being made from British EMI accounts using Baltic correspondent banks without sufficient checks being carried out on who was making them. This is similar to the scenario that occurred in the “Laundromats” exposed by the OCCRP, which resulted in billions of pounds in suspicious transactions being sent around the world." (see page 15 of this document).

Read more media here:


19/04/2022 - Last year also saw an appeals court in Paris reduce to €20 million a previous €80 million fine levied by a French court in 2017 against the bank for allegedly enabling clients of a company called France Offshore to evade taxes and launder money through companies in tax havens.

24/04/2023 - Verdict of French court on fine on Rietumu Banka for money laundering takes force
  • decision on EUR 20 million fine for money laundering has come into force

17/06/2021 - Latvian bank Rietumu fined 5.85 mln for money laundering failures 
LinkedIN Post here - https://www.linkedin.com/posts/peteroakes_fintech-electronicmoney-paymentservices-activity-7176891077675626497-X-ZI
​
  • Sign up to our Newsletter here.
  • Need assistance with an emoney or payments authorisation or an account information service provider or virtual asset services provider registration application, check out Fintech Ireland and CompliReg's handy authorisation guides at https://fintechireland.com/fintech-authorisations.html.  
0 Comments
<<Previous
Forward>>

    Author

    Fintech Ireland

    Archives

    December 2026
    September 2026
    June 2026
    May 2026
    March 2026
    December 2025
    October 2025
    September 2025
    July 2025
    March 2025
    February 2025
    January 2025
    December 2024
    November 2024
    October 2024
    July 2024
    June 2024
    May 2024
    April 2024
    March 2024
    February 2024
    December 2023
    November 2023
    October 2023
    September 2023
    August 2023
    July 2023
    June 2023
    May 2023
    April 2023
    February 2023
    October 2022
    July 2022
    June 2022
    April 2022
    March 2022
    January 2022
    December 2021
    July 2021
    May 2021
    April 2021
    March 2021
    February 2021
    January 2021
    November 2020
    October 2020
    September 2020
    August 2020
    July 2020
    April 2020
    February 2020
    July 2019
    April 2019
    March 2019
    February 2019
    January 2019
    October 2018
    September 2018
    July 2018
    June 2018
    May 2018
    April 2018
    March 2018
    January 2018
    October 2017
    September 2017
    August 2017
    July 2017
    June 2017
    May 2017
    March 2017
    January 2017
    December 2016
    November 2016
    September 2016
    August 2016
    July 2016
    June 2016
    May 2016
    April 2016
    March 2016
    February 2016
    December 2015
    September 2015
    July 2015
    June 2015
    May 2015
    April 2015
    March 2015
    September 2014
    January 2014

    Categories

    All
    Account Information Services
    AISP
    Anne Boden
    Authorisations
    #bankinginquiry
    Bank Of England
    Bitcoin
    Brian Fahey
    British Embassy Dublin
    Business Post
    CB Insights
    Central Bank Of Ireland
    Challenger Bank
    Chambers And Partners
    Competition And Consumer Protection Commission
    Compliance
    Consultations
    Contributor Articles
    Corporate Governance
    Crowdingfunding
    Crypto Assets
    Cryptocurrencies
    Currency Fair
    Cyber Security
    DeFi
    Department Of Finance
    Digital Assets
    Digital Euro
    Digital Wallets
    Directors Duties
    Disruption
    Dogpatch Labs
    Electronic Money
    EML Payments
    EMoney
    European Commission
    Financial Literacy
    Fintech
    Fintech Abu Dhabi
    Fintech Hub
    Fintech Ireland
    Fintech Ireland Map
    Fintech Ireland Summit
    Fintech Leaders Series
    Funding
    Funds
    Gemini
    Ifs2020
    Ifsc
    Innovation
    International Financial Services Strategy
    Ireland For Finance
    Irish Fintech Companies
    John Berrigan
    Kraken
    Mairead McGuiness
    Marketplace
    MiCA
    Mifid
    Moneycorp
    Money Laundering
    Monzo Bank
    MoonPay
    MyComplianceOffice
    Neobanks
    Newsletter
    Nuapay
    @oakeslaw
    OFX Payments
    Paschal Donohue
    Payments
    Payments Institution
    Paysafe
    Payward
    Peer To Peer
    Peer-to-peer
    Realex Payments
    Regtech
    Regulated Fintech
    Regulation
    Roboadvisers
    Robo Advisors
    Robo-advisors
    Ronan Gallagher
    RTE
    Sandbox
    Sentenial
    Simon Harris
    Square
    SquareUp International
    Stablecoins
    Starling Bank
    Strategy
    SYNC Payments
    The Project Foundry
    TransferMate
    Unicorn
    Unicorns
    USA Today
    Virtual Assets
    Wealthtech
    Zodia Custody
    Zodia Markets

©Fintech Ireland and ©Fintech.  Fintech Ireland (523657) and Fintech (523656) are registered with the Companies Registration Office in Ireland
www.fintechireland.com / www.fintechireland.ie / www.irishfintech.ie / www.irishfintech.com / www.fintechcareers.ie
Privacy Policy